Global palm oil market shifting away from sustainability, new report finds

Demand for palm oil is moving toward markets that care far less about deforestation, certification, and smallholder rights, according to the Global Palm Oil Outlook, a report from management consultancy NewForesight commissioned by IDH, a Netherlands based sustainable trade organization.
The study argues that sustainability progress over the past two decades was built on market conditions that are now breaking down, even as coordination gaps continue to hold back real change on the ground.
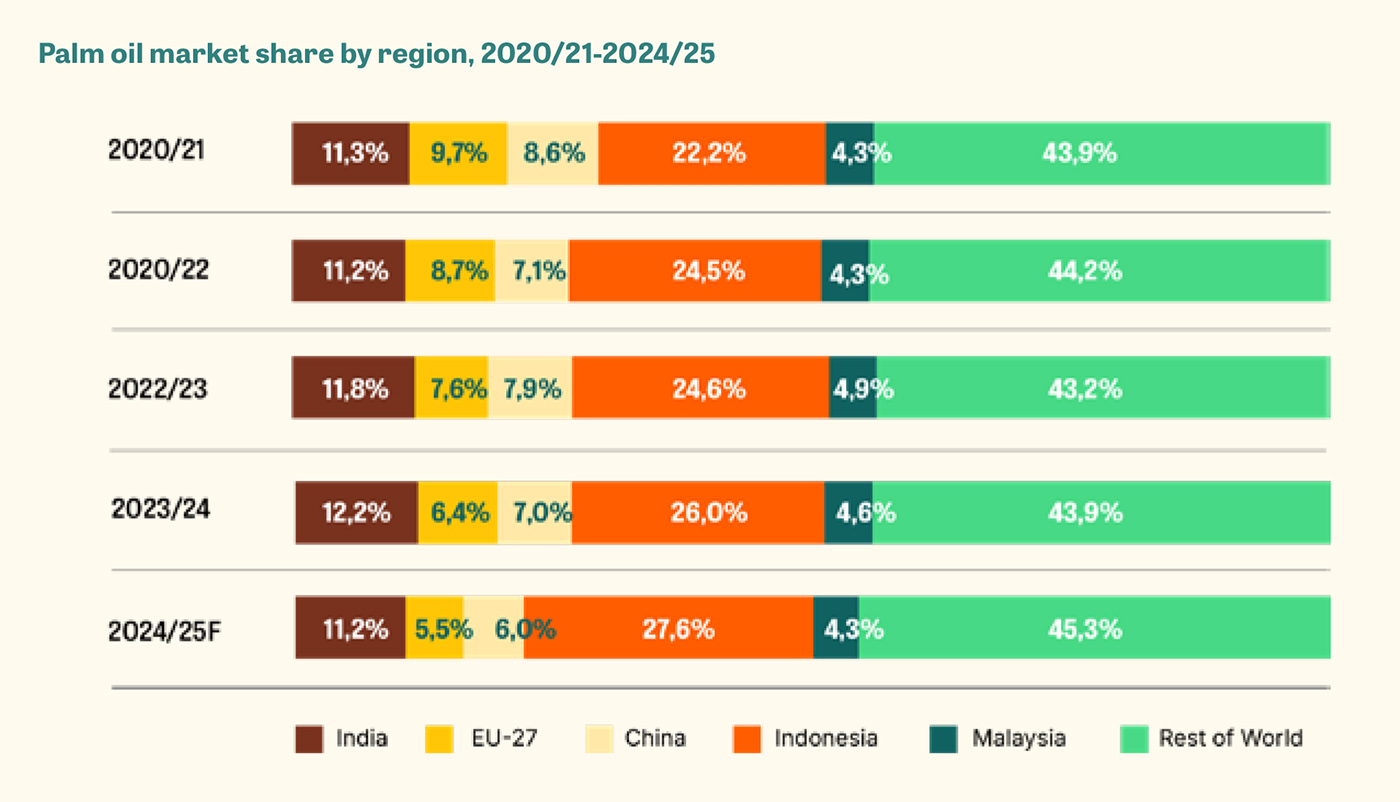
Indonesian palm oil consumption grew by 39% between the 2019 and 2020 season and the 2024 and 2025 forecast, driven largely by biodiesel and industrial use. Over that same stretch, consumption fell by 44% in the European Union and by 31% in China, two markets that historically drove certification and traceability requirements.
The result is a two-tier market. Traceable, certified supply is concentrating among a shrinking pool of sustainability-sensitive buyers, while a much larger share of volume flows toward markets where price, not sustainability credentials, decides who buys what. As evidence, the report points to 5.2 million tonnes of certified palm oil sold in 2024 without any sustainability claim attached, meaning the certification effectively went to waste once the oil entered less demanding supply chains.
Smallholders are being left behind, not pushed out
Independent smallholder farmers are not being deliberately excluded from sustainable supply chains, the report finds. They are simply unable to meet the requirements.
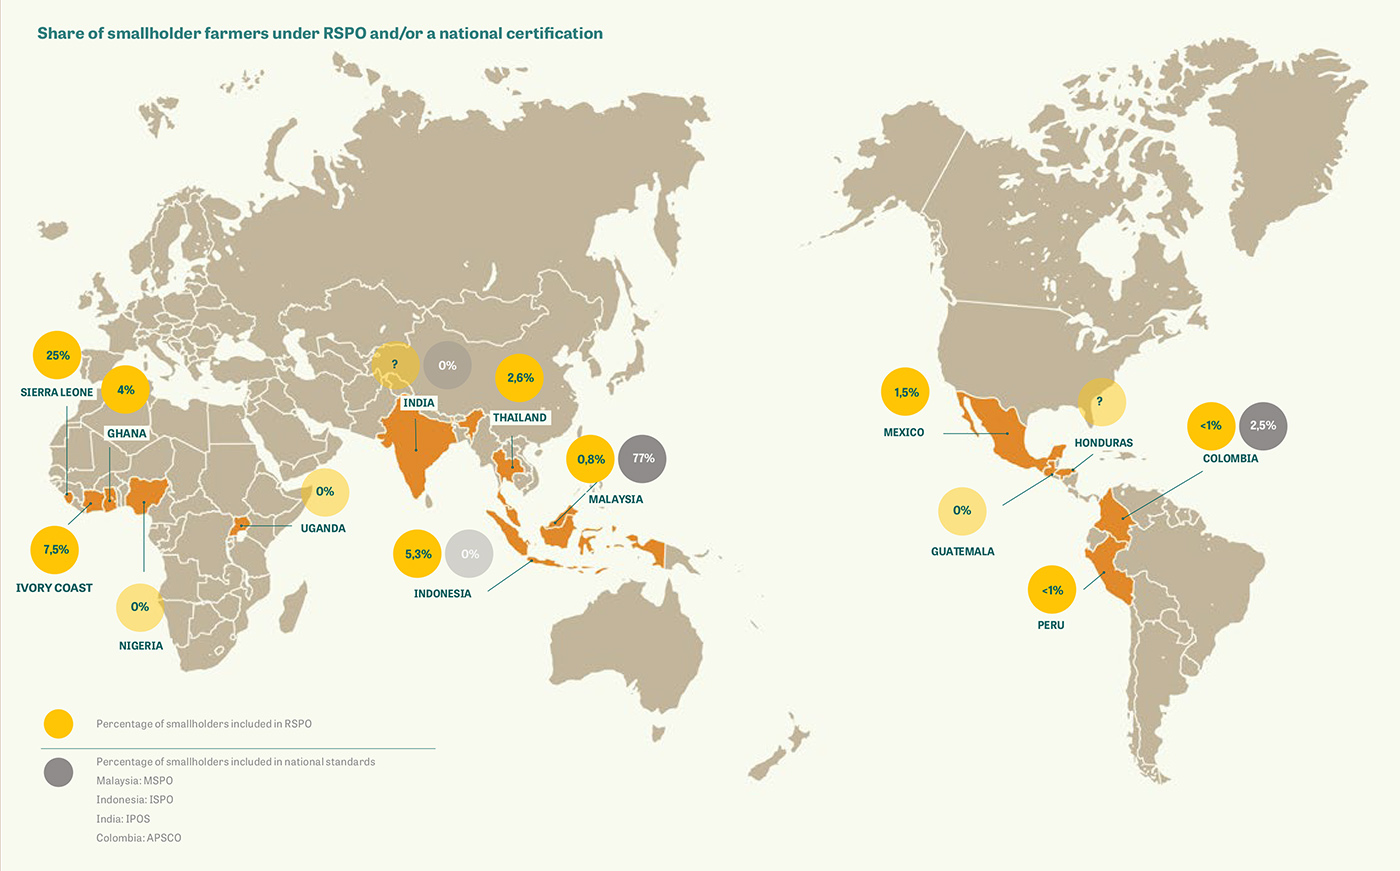
Smallholders account for an estimated 35% to 40% of global palm oil production, yet supply only 8% of palm oil certified by the Roundtable on Sustainable Palm Oil. In one readiness assessment for the European Union’s deforestation regulation, 95% of smallholder suppliers lacked the legal documentation needed to prove compliance.
Pledges have outrun proof
Among 427 palm oil companies that disclosed information through CDP, the environmental disclosure platform, 227 reported a deforestation and conversion free target, and 217 said they had assessed their sourced volumes against it.
But only 84 used a rigorous verification method, and just 36, or 8.4%, met the report’s full criteria for verified deforestation and conversion free sourcing. The report reads this as proof that public commitments have expanded far faster than the systems needed to check whether they are real.
The report argues that the biggest obstacles sit beyond what any single company or certification scheme can fix. Land registration in producing countries is often incomplete, legal documentation requirements rarely match smallholder realities, and government zoning can misclassify long-farmed land as forest. Indonesia alone needs an estimated $700 million a year to fund smallholder replanting, a cost few farmers can cover on their own.
Two models, two starting points
Two pilot programs illustrate what coordinated action can look like. In Aceh, Indonesia, a private sector-led effort involving Unilever, PepsiCo, Musim Mas, and Apical mobilized $3 million in blended finance.
Between 2019 and 2024, smallholder productivity in pilot districts rose by 69% to 104%, incomes grew two to four times over, and annual forest loss fell by 2,645 hectares. More than 4,000 smallholders received training toward certification, though the report cautions that $3 million falls far short of the $700 million needed annually across Indonesia.
In Sabah, Malaysia, government leadership drove the model instead. Since 2018, Sabah has committed 40% of state land to forest cover and mapped 100% of protected and forest areas under a shared framework, coordinated jointly across government, non-governmental organizations, and private companies. The report treats Sabah and Aceh as two entry points into the same coordination challenge, not competing approaches.
Landscape partnerships, aging trees
Companies reporting engagement in landscape initiatives through CDP rose from 27 in 2022 to 388 in 2025, and palm oil specific initiatives grew from 19 to 55. Yet only 10.1% met CDP’s criteria for a mature initiative, and about 70% of the funding still comes from Europe, North America, and Japan, the same shrinking pool of markets losing ground to producer country demand.
Beyond compliance, the report flags aging plantations as a threat to supply. In Malaysia, 27% of mature plantation area now shows declining yields, while 2.6 million hectares in Indonesia are more than 20 years old. Disease from Ganoderma, a parasitic fungus, now costs Indonesia and Malaysia more than $500 million a year combined. Replanting and better farm management, not compliance alone, represent the biggest untapped source of new supply.
What comes next
The report closes by arguing the sector is not starting from zero. Public investment in land systems, stronger demand for traceable supply, and better landscape governance are already showing results in specific places. The task now, it says, is connecting and scaling what already works, since no single actor in the supply chain can solve the coordination problem alone.